

US$750–900 Million of Brownfield Gold: A Supply-Chain Question, Not a New Plant Question
Geita, Siguiri, Cuiabá and Obuasi add capacity on existing footprints. That makes reagent consistency and delivery scheduling the governing variables.
On 5 November 2026 AngloGold Ashanti announced a three-year capital programme of US$750 million to US$900 million targeting at least 400,000 additional ounces of annual gold production by 2030 across four existing operations. Because the investment is brownfield, the leaching and adsorption circuits already exist: the incremental demand lands on reagent volumes, carbon circulation, specification consistency and delivery timing rather than on new plant design.
Etu ụzọ dị mkpa
- Brownfield, not greenfield. Four existing mines, four existing circuits — the programme raises throughput and grade control on assets already in production.
- At least 400,000 oz/y additional by 2030 is the programme-level target, with mine-level increments disclosed separately.
- Geita carries the largest allocation: US$480–580 million toward roughly 600,000 oz/y by 2030, against 492,000 oz in 2025.
- Grade decline changes reagent economics. Q3 2026 AISC of US$2,170/oz against US$1,720/oz a year earlier makes consumption per tonne a margin variable.
- Documentation gates the cyanide uzo. UN 1689 Class 6.1, an End-User Certificate and verified import permits must be closed before production slots are reserved.
- One specification across four sites is simpler to qualify, document and ship than four different reagent approvals.
| nke m | Country | Planned spend | Target |
|---|---|---|---|
| Geita | Tanzania | US$480–580m | 600,000 oz/y by 2030 (492,000 in 2025) |
| Cuiabá | Brazil | US$200–250m | +75,000 oz on a 194,000 oz base |
| Siguiri | Guinea | ~US$70m | +100,000 oz on a 289,000 oz base |
| Obuasi | Ghana | Part of programme | Target 400,000 oz/y; four operating areas by 2029 |
Company-level figures reported alongside the announcement: Q3 2026 EBITDA US$1.57 billion (up 12%), nine-month output 2.164 million ounces, full-year guidance reaffirmed at 2.8–3.17 million ounces. At a long-term gold price assumption of US$3,000/oz, management expects real internal rates of return above 35%. Q3 2026 all-in sustaining cost was US$2,170/oz against US$1,720/oz a year earlier, while average realised price rose to US$4,239/oz. Source: company Q3 2026 update and expansion announcement, 5 November 2026.
1. Why brownfield changes the reagent question
A greenfield project selects its flowsheet, then selects its reagents. A brownfield expansion does the reverse: the tanks, screens, pumps, carbon circuit and water balance are already fixed, and the extra ounces have to come through them. That means the reagent specification is not being chosen for an ideal circuit — it is being asked to hold the existing circuit stable at higher throughput, often with lower-grade feed.
The practical consequence is that consistency outranks novelty. A circuit tuned over years to a given NaCN assay, a given carbon mesh cut and a given pH band will drift if any of those inputs change. Procurement teams on brownfield programmes therefore tend to qualify one specification and hold it across the ramp-up rather than re-optimise while throughput is climbing.
2. Four procurement difficulties created by an expansion
2.1 Ramp-up timing versus documentation lead time
Capital work and reagent availability run on different clocks. Where sodium cyanide is used, the UN 1689 Class 6.1 permit chain and the End-User Certificate must be closed before a factory slot is reserved. A ramp-up date that ignores that chain creates idle circuit time.
2.2 Lower grade raises consumption per ounce
Geita's Q3 2026 output of 120,000 oz was 4% lower year on year as mined grades declined. When grade falls, more tonnes must be treated per ounce recovered, so reagent consumption per ounce rises even if consumption per tonne is steady.
2.3 Multi-site specification drift
Four mines in four countries can easily end up with four different reagent approvals, four test protocols and four freight plans. That multiplies qualification work and makes batch deviations hard to diagnose.
2.4 Cost pressure from AISC
With Q3 2026 AISC at US$2,170/oz against US$1,720/oz a year earlier, reagent efficiency is a margin line, not just a consumable. Carbon fines and impurity-driven side reactions both convert directly into cost per ounce.
3. Tutorial: six steps from added ounces to a reagent schedule
- Convert the ounce increment to ore tonnage. Divide the additional annual ounces by the expected recovered grade to estimate the extra tonnes of ore the circuit must treat. Use the plant's own recovery and grade assumptions, not a generic figure.
- Apply unit consumption by reagent. Multiply the extra tonnage by measured kg/t consumption for the leaching reagent and by the carbon make-up rate for the adsorption circuit. Both numbers should come from plant logs or a bottle roll programme.
- Add the grade-decline allowance. Where mined grade is falling, increase the tonnage estimate for the same ounce target and recalculate. This is where the Geita Q3 pattern matters.
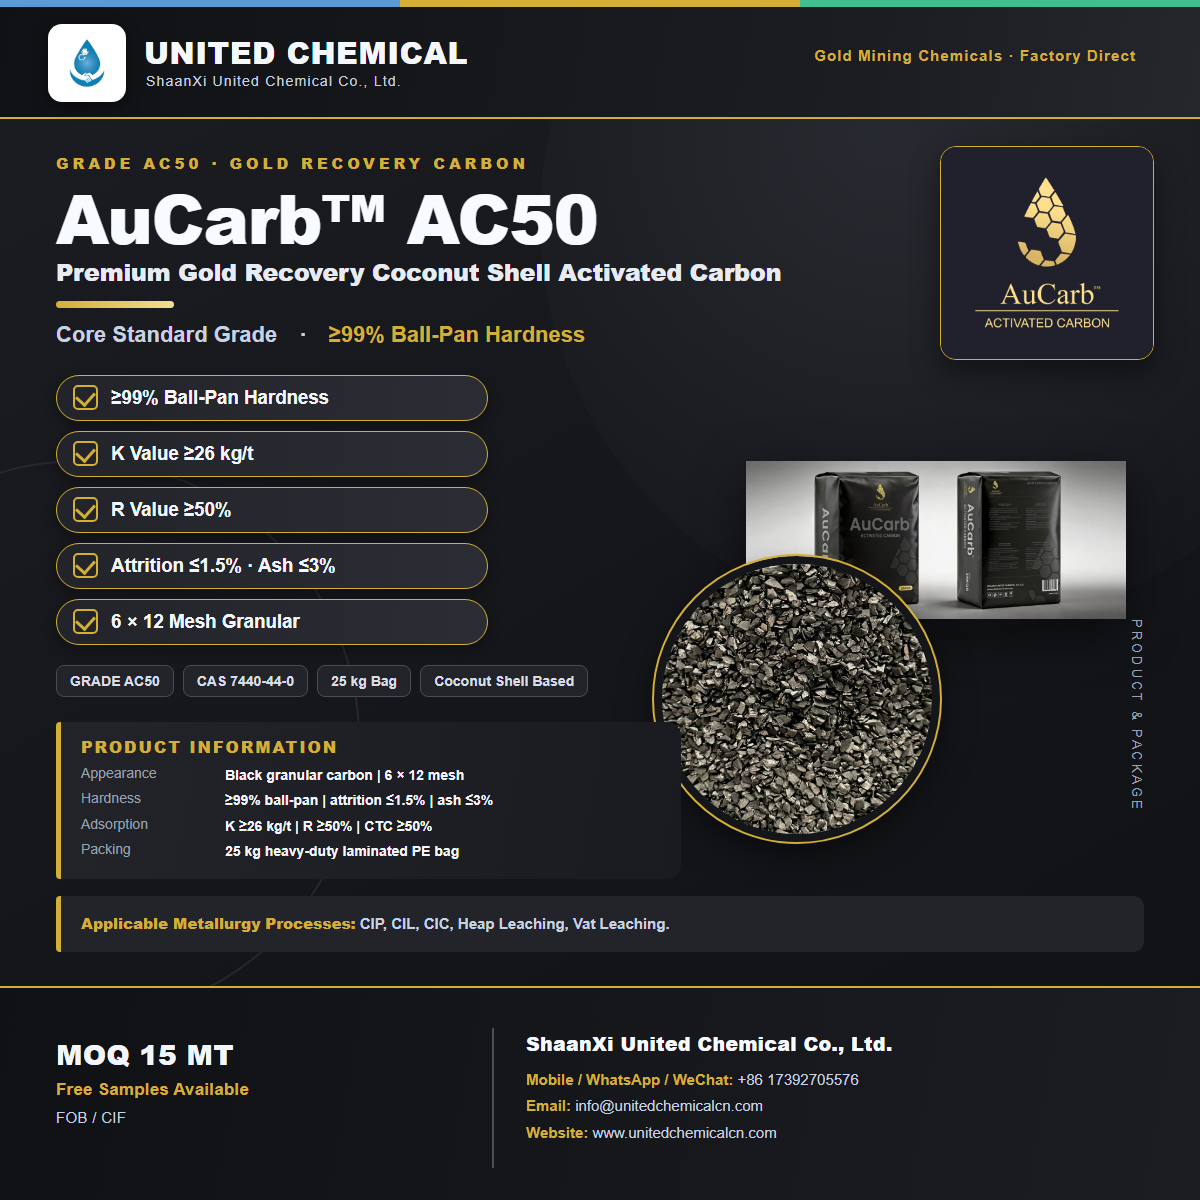
- Translate tonnage into FCLs. Divide by the applicable MOQ — 18 MT for AuCyan™ Sodium Cyanide NaCN (≥98.3%), 15 MT for AuCarb™ Gold Recovery Coconut Shell Activated Carbon (≥99% Hardness), 28 MT for AuLeach™ Gold Leaching Agent (GDA) – Non-Hazardous — to get container counts per year.
- Mepụta kalenda nnyefe against the ramp-up curve, not the nameplate date, and place the documentation gate (permit, EUC, dangerous-goods booking) ahead of the first production slot.
- Debe otu ọkọlọtọ akwụkwọ. Batch COA, TDS and MSDS per lot, one test protocol, and one FOB or CIF freight plan across the sites in the programme.
This is a planning method, not a demand forecast — the inputs are plant-specific. Its value is that it turns a headline capital figure into a procurement calendar that can actually be executed.
4. Risk register
| n'ihe ize ndụ | signal | Mwepu |
|---|---|---|
| Reagent arrives after ramp-up | Permit chain still open | Schedule EUC and import permit before factory slot |
| Consumption above plan | Grade decline, new ore blend | Re-run bottle roll and update kg/t baseline |
| Carbon losses rising | Higher circulation and screening duty | Hold attrition ≤1.5% and 6×12 mesh cut |
| Batch-to-batch drift | Multiple suppliers, multiple specs | One qualification, one COA standard per lot |
| Freight mismatch | Inconsistent Incoterms across sites | FOB or CIF only, one freight plan |
5. Where the three products sit in the expanded circuit
| ogbo | Product | Ihe mgbanwe na-emetụta mgbasa |
|---|---|---|
| Nkesa | AuCyan™ Sodium Cyanide NaCN (≥98.3%) | kg/t at higher throughput, permit scheduling |
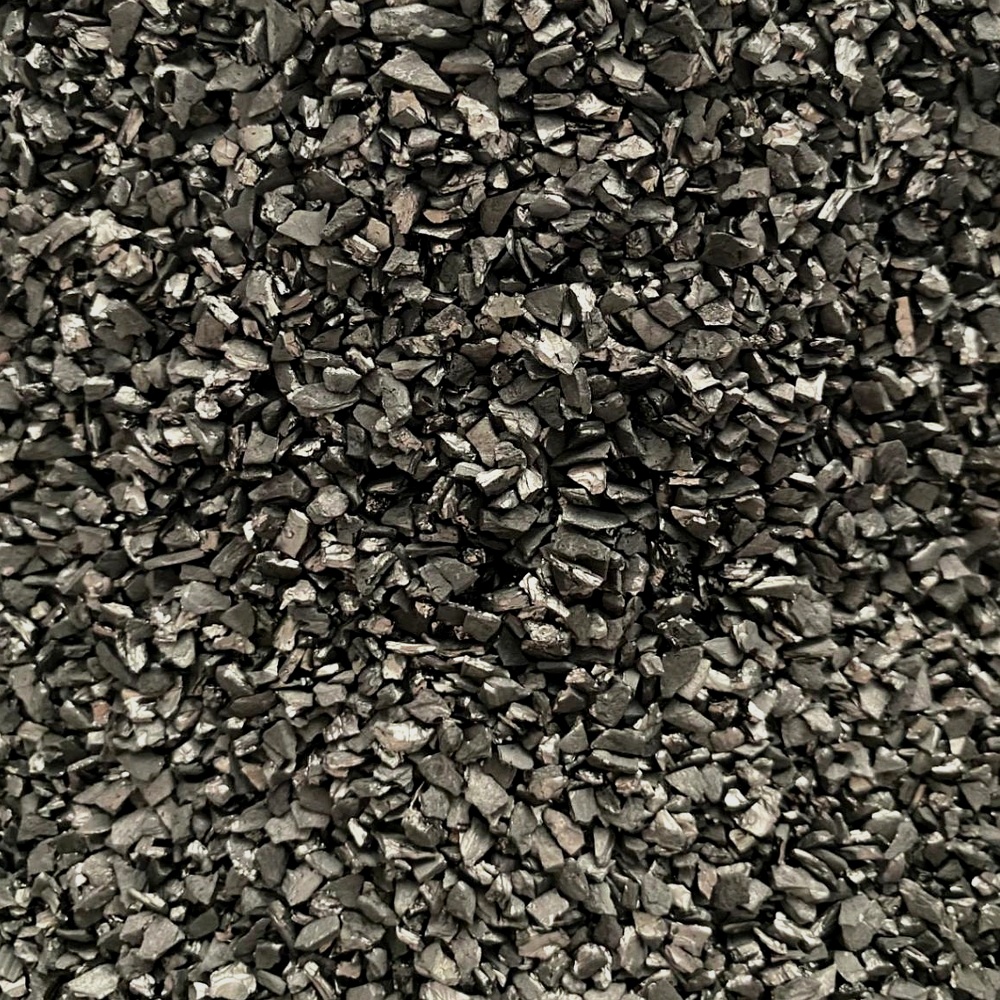
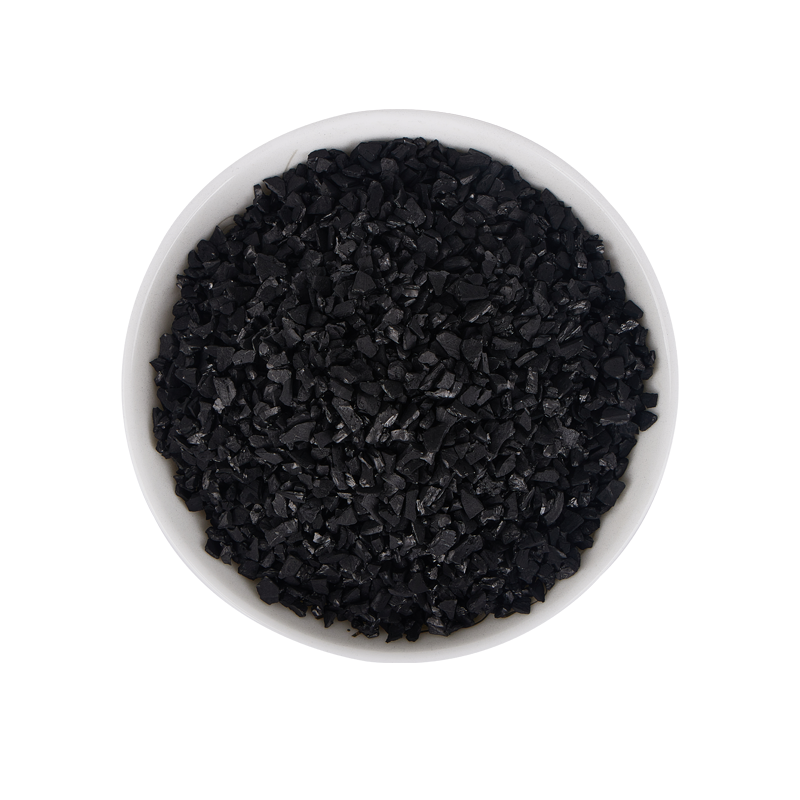
| Mgbasa ozi | AuCarb™ Gold Recovery Shell AuCarb™ Activated Carbon (≥99% Ike) | Carbon circulation, attrition, screening duty |
| Ụzọ ọzọ | Ihe Nleta Ọlaedo AuLeach™ (GDA) - Ọ dịghị akpata nsogbu | General-cargo scheduling where permits bind |
United Chemical supplies all three factory-direct under FOB or CIF terms with batch COA, TDS and MSDS, serving mining operations in more than 77 countries. Sourcing the three from one manufacturer keeps test conditions and documentation comparable across a multi-site programme.
6. Ajuju Ajuju
Q1. When was the expansion announced?
5 November 2026, alongside the company's Q3 2026 update.
Q2. How large is the programme?
US$750 million to US$900 million over three years, targeting at least 400,000 additional ounces of annual production by 2030.
Q3. Which mines are included?
Geita in Tanzania, Cuiabá in Brazil, Siguiri in Guinea and Obuasi in Ghana — all existing operations.
Q4. Why does brownfield matter for reagent buyers?
The leaching and adsorption circuits already exist, so incremental demand lands on reagent volumes, carbon circulation and delivery timing rather than new plant design.
Q5. What was the largest single allocation?
Geita at US$480–580 million, targeting roughly 600,000 oz/y by 2030 against 492,000 oz in 2025.
Q6. What does a declining grade do to reagent demand?
More tonnes must be treated per ounce recovered, so consumption per ounce rises even if consumption per tonne stays steady.
Q7. What were the Q3 2026 cost figures?
All-in sustaining cost of US$2,170/oz against US$1,720/oz a year earlier, with an average realised price of US$4,239/oz.
Q8. How do you convert added ounces into container counts?
Estimate extra ore tonnage from grade and recovery, apply measured kg/t consumption, then divide by the 15 / 18 / 28 MT minimum order quantities.
Q9. Olee akwụkwọ ndị na-egosi ụzọ cyanide?
Verified import permits and an End-User Certificate, plus UN 1689 Class 6.1 dangerous-goods documentation, ahead of the factory production slot.
Q10. Kedu Incoterms dị?
FOB or CIF terms apply to this product line.
Q11. Why hold one specification across four sites?
One qualification, one test protocol and one documentation standard make batch deviations diagnosable and reduce procurement overhead.
Q12. Where can the full product specifications be reviewed?
On the AuCyan™, AuCarb™ and AuLeach™ technical pages linked below, with batch COA, TDS and MSDS issued per lot.
7. Isi mmalite na njikọ dị n'ime
Nchịkọta nke Golden Triangle · AuCyan™ · Nduzi AuCarb™ · AC50 · AC55 · AC60 · BC1100 · AuLeach™ GDA · Nchịkọta teknụzụ nke ngwaahịa atọ · Ajụjụ kemịkalụ · Industry News · Kpọtụrụ Anyị
Source note: all company figures in this article are drawn from the AngloGold Ashanti Q3 2026 update and expansion announcement dated 5 November 2026. Reagent specifications are United Chemical product data. No figures have been estimated by the publisher.
Kpọtụrụ Anyị · WhatsApp +86 173 9270 5576 · info@unitedchemicalcn.com
- Ọdịnaya enweghị usoro
- Ọdịnaya na-ekpo ọkụ
- Ọdịnaya nyochaa na-ekpo ọkụ
- Ọla sodium, ≥99.7%
- Igwe ọkụ eletrik dijitalụ (oge igbu oge 0 ~ 16000ms)
- Calcium peroxide 60% nyocha nke mbadamba odo odo
- Kedu ka kemịkalụ Ngwuputa si emetụta ọnụego mgbake ịnweta n'oge flotation?
- TuxingSun United Mining Mineral Research and Test Center - Laboratory Testing Element
- Octyl hydroxamic acid
- sodium O, O-diethyl dithiophosphate
- 1Sodium Cyanide akwụghị ụgwọ (CAS: 143-33-9) maka Ngwuputa - Ogo dị elu na ọnụahịa asọmpi.
- 2Sodium Cyanide 98.3% CAS 143-33-9 Ihe eji achọ ọla edo NaCN dị mkpa maka ụlọ ọrụ kemịkalụ nke na-egwupụta ihe
- 3Iwu ọhụrụ nke China gbasara mbupụ sodium Cyanide na ntụzịaka maka ndị na-azụ ahịa mba ụwa
- 4Sodium Cyanide (CAS: 143-33-9) Akwụkwọ njedebe (ụdị Chinese na Bekee)
- 5Cyanide International (Sodium cyanide) Koodu njikwa - ụkpụrụ nnabata nke m ọla edo
- 6Ụlọ ọrụ China Sulfuric acid 98%
- 7Oxalic acid anhydrous 99.6% Ọkwa ụlọ ọrụ
- 1Sodium Cyanide 98.3% CAS 143-33-9 Ihe eji achọ ọla edo NaCN dị mkpa maka ụlọ ọrụ kemịkalụ nke na-egwupụta ihe
- 2Ịdị ọcha dị elu · arụmọrụ kwụsiri ike · mgbake dị elu - cyanide sodium maka ịcha ọla edo nke oge a
- 3United ChemicalNdị otu nyocha na-egosipụta ikike site na nleba anya na-ebute data
- 4AuCyan™ Sodium Cyanide Dị Elu | 98.3% Ịdị ọcha maka Ngwuputa Ọlaedo zuru ụwa ọnụ
- 5Igwe ọkụ eletrik dijitalụ (oge igbu oge 0 ~ 16000ms)
- 6Ike dị elu, nke dị elu nke ọma Shock Tube Detonator
- 7ụlọ ọrụ Electric Detonator

Ndụmọdụ ozi ịntanetị
Tinye okwu: